

It’s Tuesday morning. You’re heading to work when your car makes a sound you’ve never heard before. By lunchtime, the mechanic delivers the news: the transmission is failing. The repair will cost $3,200. You’re currently short about $2,800.
Sound familiar? For many Canadians, that moment of panic when an unexpected expense appears is exactly why emergency funds exist. It’s not about being pessimistic or anxious.
It’s about being realistic. Life happens. Cars break down. Furnaces stop working during brutal Canadian winters. Pets get sick. People lose jobs. And when those moments arrive, having even a modest amount of savings makes the difference between handling it and going into debt.
The question isn’t whether you need an emergency fund. The question is: how much do you actually need?
Here’s what we’re going to cover: The practical guidelines for emergency fund sizes, how to calculate what works for YOUR household, where to keep the money, and how to actually build it even if you’re living paycheque to paycheque. By the end, you’ll have a clear number to aim for and a realistic path to get there.
What Is an Emergency Fund?
Before we talk about how much you need, let’s be clear about what we’re actually discussing.
An emergency fund is money set aside specifically for unexpected, essential expenses.
- It’s not an investment account.
- It’s not a vacation fund in disguise.
- It’s not something you dip into when you see a sale.
- It’s a pure financial safety net.
The whole point of an emergency fund is that when something unexpected happens—something that can’t wait, something that costs real money—you can handle it without immediately reaching for a credit card or taking out a loan. That matters more than you might think.
What Counts as an Emergency?
Let’s get specific, because the line between “emergency” and “I want to buy something” can get blurry.
Actual emergencies: Job loss or reduced income, or your car needs $2,000 in repairs, and you need it to get to work. The furnace dies in January. Your dog needs emergency surgery. The roof starts leaking. Your fridge stops working. You need to fly to the hospital to see a family member. Your water heater explodes. I’m sure you get the picture.
Not emergencies: Christmas shopping (planned). Your insurance premium (predictable). That vacation you want to take (planned). New clothes (want, not need). A new phone (want, not need). Home renovations you’re considering (planned)—that sale at your favorite store (definitely not an emergency).
The real test? Can you predict it coming? If yes, it should come from a sinking fund or planned savings, not your emergency stash. Is it necessary and urgent? If no, it’s not an emergency. —
How Much Should Canadians Have in an Emergency Fund?
Here’s where most financial advice gets annoying, because someone will tell you the magic number is three months of expenses. Or six months. Or one year. And then you feel like you’re failing because you only have a hundred bucks saved.
The reality? There’s no single perfect number for every Canadian household. But there are realistic guidelines that actually work.
Start with a $500–$1,000 Emergency Fund.
If you’re living paycheque to paycheque right now, this is your target. A $500-$1,000 buffer covers smaller surprises that derail most people:
- Car repairs (not major, but real)
- Appliance repairs
- Emergency prescription costs
- Unexpected bills
- Emergency vet bills
- Urgent home repairs
This is the starter emergency fund, and it matters more than you’d think. With this cushion, a $400 car repair doesn’t immediately become a credit card debt spiral. You handle it from savings, then rebuild that $400. That’s already massively different from having nothing.
Build Toward One Month of Essential Expenses
Once you’ve hit that starter $1,000, the next goal is one month of your essential living expenses. If you spend $2,500 per month on rent, utilities, groceries, transportation, and insurance, you’re aiming for $2,500 saved.
This target matters because it covers slightly bigger problems. A job loss hits different when you know you have a full month of basic expenses covered. You have time to find new work without panicking.
Aim for 3–6 Months of Essential Expenses
This is the “gold standard” most financial advisors mention. And honestly? They have a point. Here’s why some households should aim here:
- Self-employed people: Your income varies. A 3-6-month cushion means you can handle slow months without going into debt.
- One-household income: If only one person earns income, the financial risk is higher. A larger emergency fund protects the whole family.
- Parents with dependents: More people = more potential expenses. A more emergency fund gives you breathing room.
- People with less job security: Contract work, seasonal jobs, or industries with layoffs—a bigger fund = better peace of mind.
- People with higher monthly obligations: If you carry debt, have higher rent, or have other commitments, you need more runway.
But here’s the truth: even if you don’t hit 3-6 months, having one month is genuinely solid. You’re ahead of most Canadians at that point. —
Emergency Fund Examples for Canadian Households
Let’s make this concrete. Here’s what different emergency fund sizes look like for different household expenses:
| Monthly Essential Expenses | 1-Month Fund | 3-Month Fund | 6-Month Fund |
|---|---|---|---|
| $2,000 | $2,000 | $6,000 | $12,000 |
| $2,500 | $2,500 | $7,500 | $15,000 |
| $3,000 | $3,000 | $9,000 | $18,000 |
| $3,500 | $3,500 | $10,500 | $21,000 |
| $4,000 | $4,000 | $12,000 | $24,000 |
| $5,000 | $5,000 | $15,000 | $30,000 |
See your household in there? The key is to calculate this based on YOUR expenses, not someone else’s.
💡 Real Talk: If your monthly expenses are $3,200 but someone else’s are $2,000, copying their target doesn’t help you. A $6,000 emergency fund might be amazing for them and completely inadequate for you. The math has to be personal.
Here’s what we’re going to cover: The practical guidelines for emergency fund sizes, how to calculate what works for YOUR household, where to keep the money, and how to actually build it even if you’re living paycheque to paycheque. By the end, you’ll have a clear number to aim for and a realistic path to get there.
How to Calculate Your Emergency Fund Target
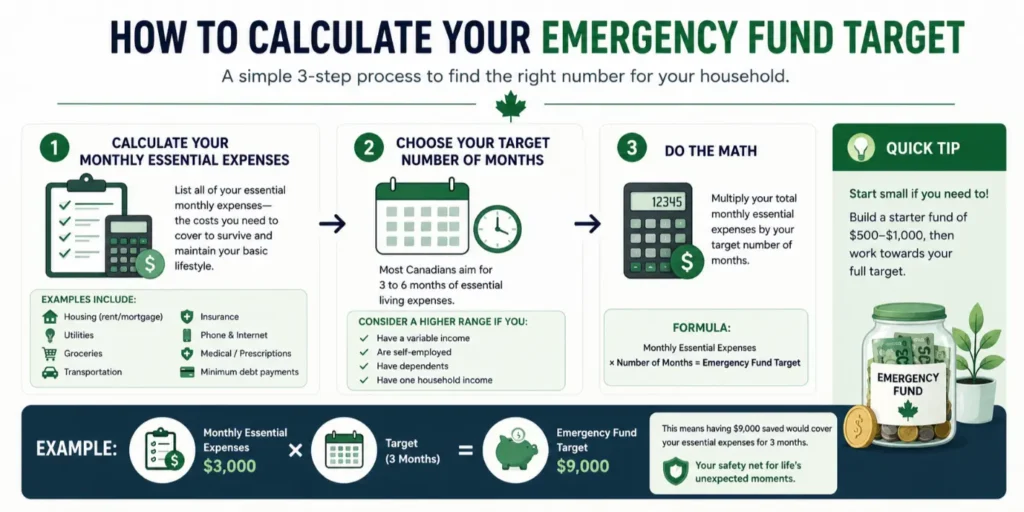
Here’s the formula. It’s simple, but accuracy matters:
Monthly essential expenses × number of months = emergency fund goal
Let’s walk through it step by step.

Step 1: Add Up Your Essential Monthly Expenses
Write down everything you actually need to spend money on each month. Essential means “I can’t skip this, or bad things happen.”
- Rent or mortgage payment
- Utilities (hydro, gas, water)
- Groceries and essential food
- Transportation (car payment, insurance, gas, or transit)
- Insurance (home, health, life)
- Minimum debt payments (credit cards, loans)
- Phone and internet
- Childcare (if applicable)
- Medication and essential health costs
- Any other truly necessary household expense
Add all of that up. That’s your monthly essential expenses number.
Step 2: Separate Needs From Wants
This is where people get stuck, because they conflate “expenses I actually spend money on” with “essential expenses.”
Here’s the difference:
Needs: Rent or mortgage. Utilities. Groceries. Transportation to work. Minimum debt payments. Phone for emergencies. Medicine you actually take.
Wants: Streaming services. Restaurant meals. Entertainment. Non-essential shopping. Premium phone plans. Gym membership. Subscriptions you could cancel.
Your emergency fund needs to cover needs, not wants. This is important because it means your emergency fund target might be smaller than your current monthly spending.
If you spend $3,500 per month, but $800 of that is for streaming services, restaurants, and shopping, your actual emergency needs are $2,700. That matters when calculating how much you need to save.
Step 3: Choose Your Target
Now you decide. Do you want:
- $500-$1,000? A starter fund to cover small surprises.
- One month? A solid foundation that handles job loss scenarios.
- Three months? A comfortable cushion for most situations.
- Six months? A robust safety net for variable income or higher risk.
Pick the target that matches your situation. Then multiply your monthly expenses by that number. That’s your goal. —
How Much Should YOU Keep in an Emergency Fund?
Okay, numbers are great, but your actual target depends on your actual situation.
If You Have a Stable Job
Stable job + regular paycheques + hard to get fired + reasonable job security? You can probably get by with one month or maybe three months of expenses. The risk of sudden income loss is lower, so you don’t need as much cushion.
If You’re Self-Employed
Your income varies month to month. Some months are great, some months are slow. This is literally why self-employed people need bigger emergency funds. Six months is reasonable. Sometimes even more. You need that buffer to handle the slow months without panicking or going into debt.
If You Have Children or Dependents
More people = more potential expenses. School emergencies—medical costs. Increased risk. One month might feel tight. Three to six months feels more realistic.
If You Have One Household Income
All your financial stability rests on one person’s job. If that income stops, everything stops. A bigger emergency fund (three to six months) protects your entire household from a single job loss.
If Your Income Fluctuates Seasonally
Seasonal work means you have predictable lean months. Your emergency fund needs to cover those lean months without having to borrow. This might mean more than six months if your seasonal swings are extreme.
The right emergency fund size isn’t the one financial advisors recommend. It’s the one that lets YOU sleep at night.
Where Should You Keep Your Emergency Fund?

This matters. A lot of people save money, but then put it somewhere that defeats the purpose.
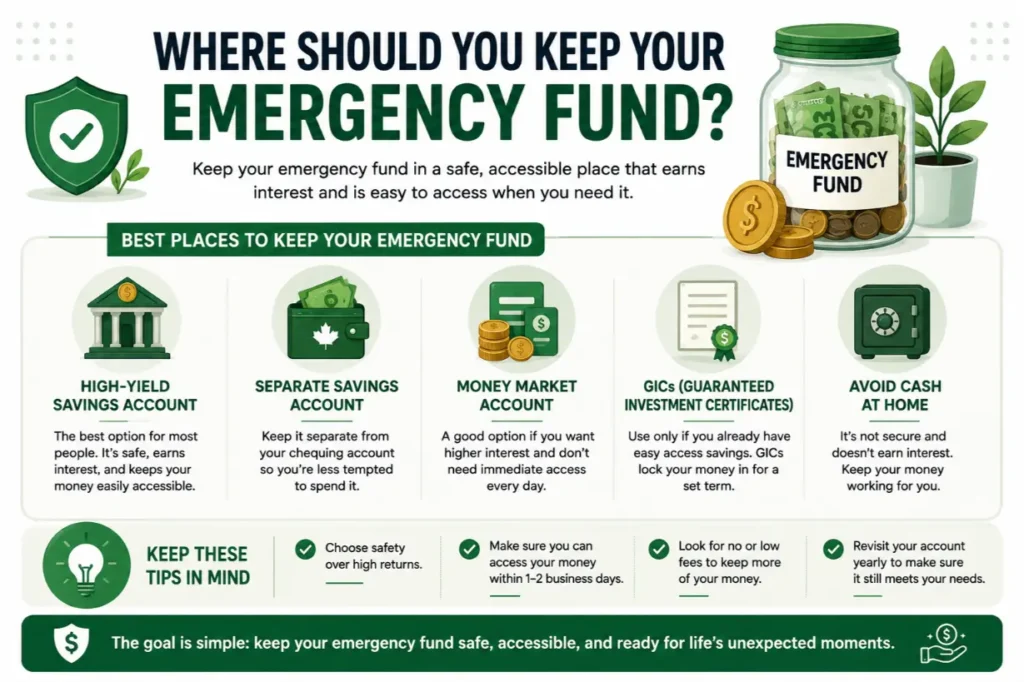
Your emergency fund needs to be two things:
- Safe: The money shouldn’t fluctuate or disappear.
- Accessible: You can get it quickly without penalties or complicated processes.
This means don’t invest it in stocks. Don’t put it in GICs that lock up your money. Don’t hide it somewhere that takes weeks to access. An actual emergency means you need the money now.
Good options for emergency funds:
- High-interest savings account (HISA): Your money is safe, accessible, and earns interest. Most Canadian banks offer these. Currently, rates are decent for savings accounts.
- Regular savings account: Less interest than a HISA, but completely safe and instantly accessible.
- TFSA (Tax-Free Savings Account): You can hold cash or HISAs in a TFSA. Money stays accessible, you don’t pay tax on interest, and you preserve regular income-splitting flexibility.
Keep it separate from your daily spending account. This is important. If your emergency fund lives in the same account as your grocery money, you’ll accidentally use it for non-emergencies. Create a separate bank account you don’t see every day.
Should Your Emergency Fund Be in a TFSA?
This is a reasonable question. TFSAs are flexible and allow tax-free growth.
Pros:
- Money is accessible at any time
- Interest earnings aren’t taxed
- You can withdraw and re-contribute later
- Good option for emergency money
Cons:
- Uses your TFSA contribution room (which is limited)
- You might be better off using the TFSA room for investments that earn more over time
- If you’re also saving for retirement, you’re choosing between emergency money and retirement growth
The bottom line: A TFSA or HISA is a fine home for emergency money, but consider whether you have other savings priorities that the TFSA contribution room might better serve. —
Emergency Fund vs. Other Savings Goals
Here’s where priorities get complicated. Most Canadians aren’t trying to save just one thing. You want to fund emergencies, plan a vacation, save for retirement, and build a down payment for a house. All at once.
Let’s be honest about what matters:
| Savings Goal | Purpose | Priority |
|---|---|---|
| Emergency Fund | Unexpected essential expenses | High |
| Sinking Funds (car maintenance, annual insurance) | Predictable expenses you know are coming | High |
| Retirement Savings | Long-term financial security | High |
| Debt Repayment | Reduce interest payments and financial risk | High (especially high-interest) |
| Vacation Fund | Planned travel (nice to have) | Optional |
| Home Improvement Fund | Planned renovations (can wait) | Optional |
Notice that the emergency fund is a high priority. That’s intentional. You can’t effectively work toward other goals if you keep derailing yourself with emergency debt when surprises happen. —
What If You Can’t Afford a 3–6 Month Emergency Fund?
Real talk: Most Canadians don’t have $18,000 sitting around. If that’s you, that’s normal, not a personal failure.
Here’s the good news: something is infinitely better than nothing.
Start With What You Can
Even:
- $5 per week ($260 per year)
- $25 per paycheque ($650 per year if paid biweekly)
- $50 per month ($600 per year)
- Whatever you can spare without going hungry
If you save $50 per month, you hit $1,000 in 20 months. That’s significant. That’s life-changing when an emergency happens.
The key is starting. Not starting because you can’t hit $18,000 immediately is like not exercising because you can’t run a marathon. The person with $100 saved is ahead of the person with $0, period.
Automate Your Savings
The best emergency fund-building hack: automatic transfers on payday.
Set up your bank to transfer $25 or $50 from your chequing account to your savings account the same day you get paid. You never see it in your regular account. It just disappears into savings. After a few weeks, you stop noticing. After a few months, you’re shocked at how much you’ve saved.
Seriously. This works.
Use Windfalls Carefully
Tax refunds. Work bonuses. Cash gifts. Side income—money from selling unused items.
These are emergency fund opportunities. Not because you have to put every cent there, but because these windfalls are emotionally easier to save. You didn’t miss the money while earning it, so it doesn’t feel like a sacrifice to save it.
A $500 tax refund dropped into emergency savings is $500 closer to your goal. That matters. —
How to Build an Emergency Fund on a Tight Budget
You’re living paycheque to paycheque. Real question: how do you build emergency savings at all?
Start small, but start:
- Set a tiny initial target: $500 instead of $3,000. Hit that, then reassess.
- Automate even small amounts: $10-$25 per paycheque adds up faster than you think.
- Review subscriptions: Netflix, gym, app subscriptions. Cancel things you don’t use. That $50/month in savings = emergency fund growth.
- Reduce food waste: Plan meals. Don’t buy things that rot. Eat what you have before buying more.
- Meal plan strategically: Cheap meals like rice and beans, pasta with sauce, bulk soup. Real food that costs less.
- Keep unexpected money: overtime paycheques, bonuses, tax refunds, gift money. All of it goes to the emergency fund until you hit your target.
- Sell stuff: Old clothes, furniture, electronics. Kijiji, Facebook Marketplace. You’d be surprised what people will buy. That $50 from old sweaters is emergency fund money.
- Track progress visually: Chart, jar, spreadsheet. Seeing the number grow is motivating.
- Increase savings when income increases: Raise? Bonus? Side income success? Increase emergency fund contributions before you get used to spending that money.
None of these is glamorous. But they work. —
Should You Pay Off Debt or Build an Emergency Fund First?
This is the question that keeps people up at night. You have $200 to spare. Do you pay toward credit card debt or emergency savings?
Here’s the honest answer: It’s not “all debt first” or “all savings first.” It’s both, strategically.
Priority 1: Build a small emergency cushion ($500-$1,000)
Why? Because without this cushion, the next surprise sends you deeper into debt. You build the emergency fund, then hit pause.
Priority 2: Attack high-interest debt aggressively
Credit cards charging 19%+ interest are costing you money daily. Pay them down hard while maintaining that $500-$1,000 emergency cushion.
Priority 3: Build an emergency fund for one month of expenses
Once high-interest debt is under control, expand your emergency fund while paying only the minimum on other debt.
Why this order? Because you need to break the cycle where surprises = emergency debt. The small emergency cushion does that. Then you eliminate the expensive debt. Then you build more cushion.
Why Even Small Emergency Savings Matter
Imagine this: You have a $500 emergency fund. Your car breaks down. The repair costs $400. You use your emergency fund, you hit some financial breathing room, then you rebuild that $400. Problem solved.
Compared to: You have no emergency fund. The $400 repairis charged to a credit card at 19% interest. Monthly payments start. Months later, you’re still paying $20/month in interest alone. That emergency has cost you over $100 in interest by the time it’s paid.
The person with the emergency fund avoided hundreds of interest charges. That’s not luck. That’s math. —
When Should You Use Your Emergency Fund?
This seems obvious, but it’s worth being specific.
Good reasons to use emergency funds:
- Unexpected car repair you need to work on
- Job loss
- Urgent home repair (roof, plumbing, heating)
- Major medical or dental emergency
- Essential appliance replacement (refrigerator, water heater)
- Unexpected travel for a family emergency
- Genuine financial emergency you didn’t predict
Not-so-good reasons to use emergency funds:
- There’s a sale
- You want a vacation
- Your friends are going out, and you want to join them
- You see something you like
- You’re bored
- Normal bills you should have planned for
The distinction: Could you predict it? Can it wait? Do you actually need it? If answers are yes/yes/no, it’s not an emergency.
What to Do After Using Your Emergency Fund
You had to use it. That’s fine. That’s literally what it’s there for. Now what?
Step 1: Stabilize
Handle the crisis. Make sure the immediate problem is solved. Don’t worry about rebuilding the fund yet.
Step 2: Take a breath
You just used savings during a crisis and handled it without taking on debt. That’s not failure. That’s exactly what emergency funds do.
Step 3: Rebuild
Go back to your automatic transfers. Start rebuilding that fund. If you had $3,000 saved and used $2,000, you’re rebuilding from $1,000. Your goal is $3,000 again.
It might take a few months. That’s okay. You’re still ahead of where you’d be if you were in emergency debt. —
How Often Should You Review Your Emergency Fund?
At a minimum, once a year. But also whenever major life things change:
- You moved, and your rent/mortgage changed
- You had a child (or children moved out)
- You changed jobs (especially if income changed significantly)
- You became self-employed
- You took on a major loan
- You paid off a mortgage or loan
- Your household income dropped significantly
- You had unexpected large expenses that changed your monthly budget
When any of these happen, recalculate your essential monthly expenses and determine if your emergency fund target should change. —
Frequently Asked Questions About Emergency Funds
Is $1,000 enough for an emergency fund?
It’s a good starter, but probably not enough in the long term. $1,000 covers small surprises. If you lose your job or have a major repair, $1,000 disappears fast. It’s a foundation, not a final answer.
Is $5,000 a good amount for an emergency fund?
Depends entirely on your monthly expenses. If you spend $2,000/month, $5,000 is over two months—solid. If you spend $4,000/month, it’s just over a month. The number only matters in context.
Is 3 months of expenses enough?
For many people, yes. If your job is secure, you’re employed by someone else, and you don’t have major dependents, three months is reasonable. If you’re self-employed or have higher expenses, six might be better.
How much should a family of four have in emergency savings?
Calculate what four people actually need per month (rent, food, transportation, etc.), then multiply by three or six. There’s no universal number. Your family’s number depends on your family’s expenses.
Should I keep my emergency fund in cash?
Physical cash at home? No. That’s not safe, and it earns no interest. But you should keep it instantly accessible—savings account, HISA, etc. Not locked in investments or GICs.
Should I invest my emergency fund?
No. Emergency money shouldn’t be in the stock market or any fluctuating investments. You might need it tomorrow, and you can’t afford for it to be down 10% that day.
Where should I keep my emergency savings in Canada?
A high-interest savings account is usually best. Look for accounts that offer:
- No monthly fees
- Interest paid regularly (even small amounts help)
- Instant access to your money
- CDIC protection (up to $100,000)
Major Canadian banks, online banks, and credit unions all offer these. Compare rates at ratehub.ca or your bank’s website.
What if I have no emergency fund yet?
Start today. Not next month. Not when you get that raise. Today. Even $5 into a separate savings account is forward motion. Build from there. —
Final Thoughts: Your Emergency Fund Doesn’t Have to Be Perfect
Here’s what we’ve covered:
- No magic number works for everyone.
- Your household is different from your neighbor’s household.
- Your job security is different. Your monthly expenses are different.
- Your circumstances are different.
The point isn’t to hit some perfect target and then stop thinking about it. The point is to have enough so that life’s surprises don’t immediately become debt crises.
Remember this:
- Start with $500-$1,000 if you’re beginning
- Work toward one month of essential expenses as a solid foundation
- Consider three to six months as a longer-term goal based on your situation
- Your personal circumstances matter way more than generic advice
- Rebuilding after using your fund is normal and fine
- Progress matters infinitely more than perfection
- Someone with $100 saved is ahead of someone with $0
Remember this:
- Start with $500-$1,000 if you’re just beginning
- Work toward one month of essential expenses as a solid foundation
- Consider three to six months as a longer-term goal based on your situation
- Your personal circumstances matter way more than generic advice
- Rebuilding after using your fund is normal and fine
- Progress matters infinitely more than perfection
- Someone with $100 saved is ahead of someone with $0
Your emergency fund doesn’t have to be perfect. It just has to exist, and it has to grow. That’s it. —
Question: Where do you keep your emergency savings so they are accessible when you need them? Leave me your answer in the comments.
Thanks for reading,
Mr. CBB
Ready to Build Your Emergency Fund?
free Emergency Fund Calculator & Savings Tracker to calculate your exact target and monitor your progress.
Emergency Fund CalculatorOr read more about building wealth at Canadian Budget Binder. We’ll help you every step of the way.
—
This post may contain affiliate links to products or services we recommend. We may receive a small commission if you purchase through these links, at no extra cost to you. This helps us continue creating helpful content for Canadian households.